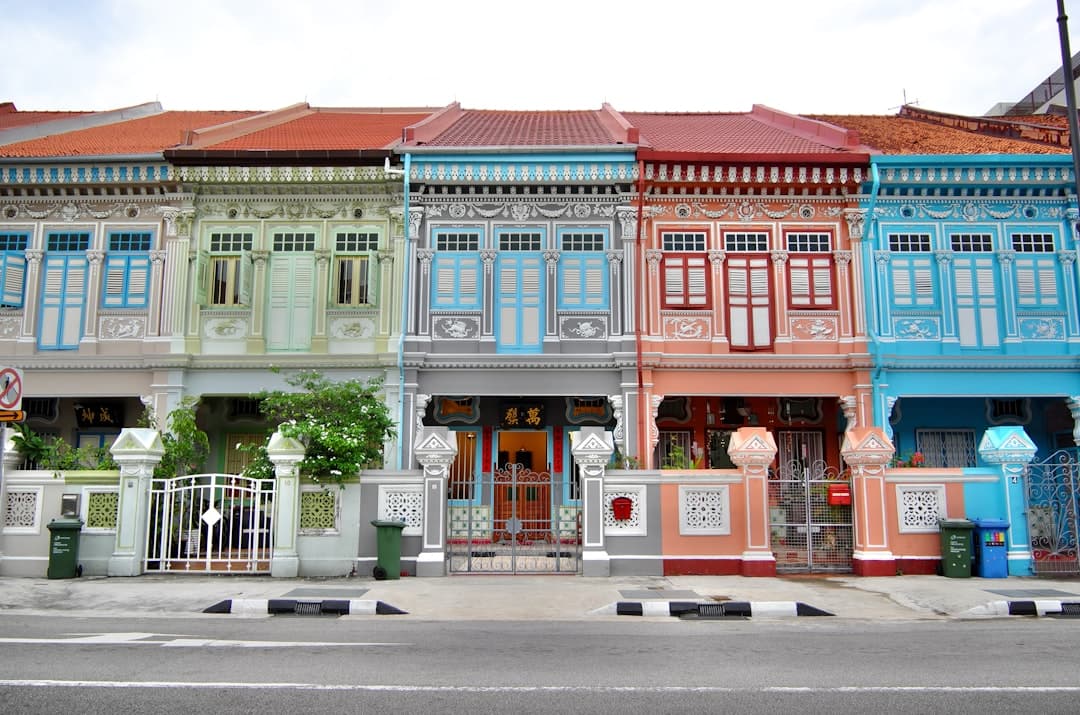
 Photo by Kate Branch on Unsplash
You own a terrace house in Buona Vista or a semi-detached in Upper Thomson. The asset is worth $7M to $9M on a recent desktop estimate, and you need to access a meaningful slice of that equity: to fund an investment, complete a purchase, or settle a time-sensitive obligation.
Your relationship bank comes back with 40% to 45% LTV. Not because your credit is weak. Because the regulatory loan-to-value cap on a second housing loan, the income test, and a cautious landed valuation all stack on top of each other.
The mismatch between what your landed asset is worth and what a bank will lend against it is the specific problem this article addresses, and why private bridging is often the rational answer for landed property owners who need to move quickly.
Why Banks Apply a Deeper Discount to Landed Property
The 40% to 45% ceiling is regulatory before it is anything else. MAS caps the loan-to-value ratio at 45% where the borrower already has one outstanding housing loan, and 35% where there are two or more. Most landed owners who approach us are in exactly that position, so the facility is capped at 45% before a valuer has looked at the lot.
TDSR sets the second limit. Total debt servicing cannot exceed 55% of gross monthly income, and the servicing cost on even a 45% facility against a $7M asset is substantial. A borrower whose income arrives as directors' fees, dividends or distributions often fails the test on declared figures, and the offer is cut again.
Valuation conservatism is the third factor, and it compounds the first two rather than causing them. A condominium unit is relatively straightforward to value: sales data for comparable units in the same development is available, recent and consistent. Landed property works differently.
URA classifies Singapore landed residential into several tiers: terrace houses, semi-detached homes, detached bungalows and GCBs. Within each tier, every lot differs in size, orientation, road-line setback, and redevelopment potential. Valuers therefore have fewer true comparables to anchor against, and standard practice when comparables are sparse is to build in a liquidity buffer, a discount reflecting that a landed lot may take longer to sell if the bank needs to realise security.
The result is structural, not personal. A borrower with a clean credit record and one existing housing loan is capped at 45% by rule, trimmed by the income test, and then measured against a figure a valuer has deliberately set on the cautious side.
What Private Bridging Offers Instead
We lend against the asset and a credible exit, not against income. TDSR does not apply to private lenders, so the income test that constrains a bank's offer is not a factor. The ceiling is the asset's value and the strength of your exit: typically a sale, a bank refinance once a full valuation has been done, or the realisation of another asset.
On Singapore landed property (including terrace houses, semi-detached homes, and detached bungalows outside the GCB tier) we can lend up to 70% LTV. For the GCB tier, the same framework applies but the security, ticket size and ownership rules differ; our GCB bridging loan page covers that product separately. If the LTV gap is your specific problem, speak to our team with a property address and a rough valuation. A same-day indication of terms is considered case by case.
Term sheets are typically issued within 24 hours of a complete request. Drawdown typically follows in about two weeks for a standard Singapore landed loan, or inside seven days when the property is clean and there are no title complications. For a step-by-step view of what happens between enquiry and drawdown, our lending process page sets out each stage.
When Bridging a Landed Property Makes Sense (and When It Does Not)
A bridge works when the bank's LTV offer materially undershoots what you need, and when you have a credible exit within the loan term. The exits we see most often against Singapore landed property are: a confirmed sale of the security or another asset; a bank refinance after a completed valuation; or a known liquidity event, such as a business sale or structured redemption, timed within the loan window.
If none of those exits is credible within 3 to 24 months, a bridge is the wrong instrument. The cost of private credit is higher than a bank mortgage, the term is short by design, and it is not a substitute for a long-term capital structure. A borrower who cannot articulate an exit should address that question before enquiring.
The main risk is straightforward: if the exit stalls, the loan must be extended or the security realised. We work constructively with borrowers who run into timing friction, but the exit must be real at the outset. Related: read our guide to equity release on luxury Singapore property.
Practical Considerations Before You Apply
Eligibility is limited to Accredited Investors and corporates. The property pledged as security must be Singapore-registered landed residential. The borrower, or the SPV holding the property, must be in a position to grant a first charge.
A professional valuation will be commissioned on your behalf. Your bank's earlier figure is a useful reference point, but terms are agreed on the basis of an independent assessment. Request a term sheet and we will typically confirm the parameters within 24 hours; drawdown follows once valuation, title review, and KYC are complete.
For product parameters on bungalow and landed security, our bungalow bridging loan page sets out the detail. For a deeper look at how private lending sits outside the TDSR framework, the article on bridge loans without TDSR in Singapore covers the mechanics. The key question we assess first is simple: what is the asset, and what is the exit.
Get Funding Approval Within 24 Hours
Speak with our specialists about your bridging requirements.
Frequently asked questions
Article sources2
Rikvin Capital cites primary, authoritative sources to support the information in our articles. The references below link directly to the original material.