Condominium Bridging Loans
Our Condominium Bridging Loans are designed to provide quick, flexible funding for buyers and investors looking to complete their private apartment purchase or refinance a condo asset. Whether you're upgrading to a new condominium or unlocking liquidity from your current unit, we offer bespoke facilities from $1 million to $100 million, with swift approvals, competitive rates, and transparent terms.
Use Cases
Auction Purchases
Speed is crucial when buying at auction—our bridging loans help you meet strict deadlines.
Commercial & Mixed-Use Acquisitions
Secure prime commercial or mixed-use properties without losing out to competition.
Business Cash Flow
Use property equity to finance expansion or meet short-term obligations.
Short-Term Refinancing
Consolidate or refinance existing property finance until a long-term solution is arranged.
Why Choose Rikvin Capital?
Fast Turnaround
Our dedicated team can issue a term sheet within 24 hours, and deliver funds within just 2 weeks—minimizing delays and uncertainty.
Flexible Terms
We offer up to 70% LTV, with interest roll-up options to help manage cash flow.
Large-Scale Funding
Borrow up to 100 million to seize high-value opportunities that traditional lenders might not be able to support.
Approachable Experts
With extensive experience in bridging finance, our team works closely with you to understand your goals and structure a deal that fits.
How It Works
- 1
Enquire
Share the asset, the amount you need and your intended exit with our team, by enquiry form or WhatsApp.
- 2
Term sheet within 24 hours
Where the collateral, amount and exit are clear, you receive an indicative term sheet within 24 hours.
- 3
Funds in about two weeks
Valuation, legal review and completion typically take about two weeks on clean deals.
Get Funding Approval Within 24 Hours
Case Studies
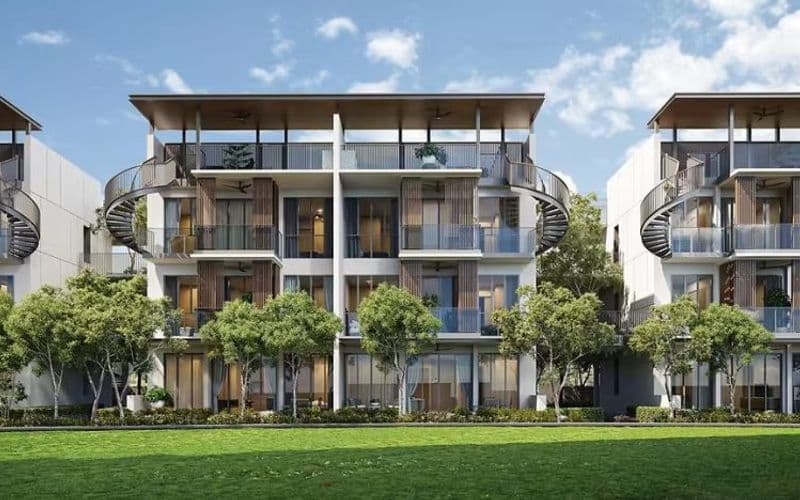
Prime Residential Bridging Loan for Holland Road Property
- Loan Amount
- SGD 5.7M
- Asset
- Semi-detached house
- LTV
- 70 %

Good Class Bungalow GCB Bridging Loan for Binjai Park Property
- Loan Amount
- SGD 20M
- Asset
- Good Class Bungalow
- LTV
- 66.9 %
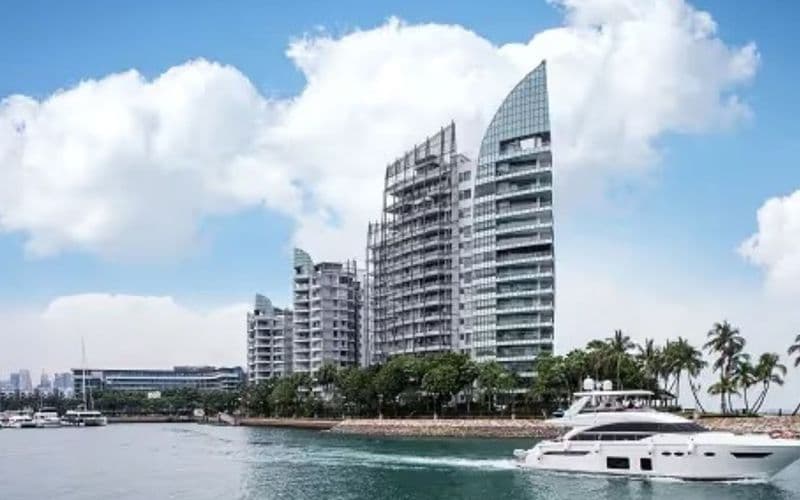
Breaking the Sentosa Property Lending Freeze
- Loan Amount
- Confidential
- Asset
- Asset-backed collateral
- LTV
- Not disclosed
Weekend Rescue: How we Delivered $25 Million Bridge Funding for a Billionaire’s Acquisition
- Loan Amount
- Confidential
- Asset
- Asset-backed collateral
- LTV
- Not disclosed
Successful Bridge Loan Solutions for Prime Geylang Property
- Loan Amount
- Confidential
- Asset
- Asset-backed collateral
- LTV
- Not disclosed
Sentosa Saga: Tailored Bridge Financing in Action
- Loan Amount
- Confidential
- Asset
- Asset-backed collateral
- LTV
- Not disclosed
Empowering Established Brands: Our Bridge Funding Success Story
- Loan Amount
- Confidential
- Asset
- Asset-backed collateral
- LTV
- Not disclosed
Unlocking $25 Million: Alternative Bridge Financing for Prime Property Owners
- Loan Amount
- Confidential
- Asset
- Asset-backed collateral
- LTV
- Not disclosed
Rikvin Capital’s Bridge Loan Solution for Prime Commercial Property Purchase: A Client’s Success Story
- Loan Amount
- Confidential
- Asset
- Asset-backed collateral
- LTV
- Not disclosed
FAQs
Compare the full product range on our bridging loans in Singapore page.