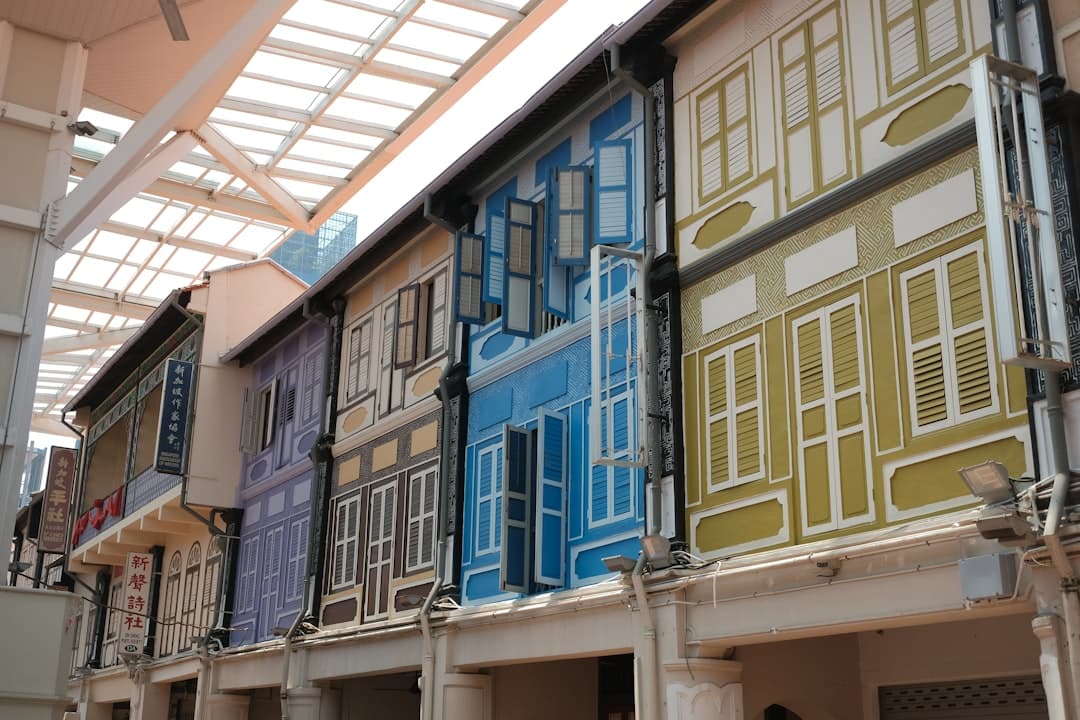
 Photo by Angelyn Sanjorjo on Unsplash
Your bank declined. Not because the shophouse or strata office you want is overpriced, or because your balance sheet is weak. The reason is simpler: your residential mortgages, the family home and perhaps a condo investment, have pushed your TDSR past the 55% limit.
This is the point where Singapore's HNW investors run into a wall. Banks apply the TDSR framework to property loans across the board, commercial or residential, and once you hit the threshold, the income calculator does not move regardless of how strong the underlying asset is.
Bridge lenders for commercial real estate start from a different question. Not "can this borrower service this debt from income?" but "is the asset solid, and is the exit credible?" That shift in underwriting logic is what opens the door.
Why TDSR Blocks Commercial Acquisitions
Many investors assume TDSR is a residential safeguard. In practice, banks in Singapore apply it to all property loans extended to individuals. A strata office acquisition, a shophouse purchase, an industrial unit: each draws from the same 55% headroom as your family home's mortgage.
Once you are at or near the ceiling, the bank must decline. Not because the commercial deal is flawed, but because the income-to-debt calculation says it cannot proceed. The MAS framework is a system-level control, not an asset-by-asset judgement call.
That is exactly where bridge lenders for commercial real estate operate differently. As excluded moneylenders lending only to accredited investors and corporates, they underwrite the asset and the exit. The assessment covers LTV, rental covenant, market liquidity, and disposal timeline, not an income-ratio ceiling.
How a Commercial Bridge Is Structured
At Rikvin Capital, a shophouse bridge loan or strata office bridge facility begins with the asset and the exit. What does the independent valuation say? What is the LTV? How does the borrower exit within the agreed term?
Loan sizes run from $1M to $100M, with LTV up to 70% on qualifying Singapore commercial assets. Terms are 3 to 24 months. Interest can be rolled up, so there is no monthly cash servicing requirement during the facility. Lending on a vacant or part-let unit is considered case by case, subject to terms; where it is agreed, rolling up interest gives you time to secure a lease before conventional refinancing.
If you have a deal in view, share the details with our team for an indicative term sheet within 24 hours. Drawdown typically completes in about two weeks, though urgent situations have completed inside seven days.
What Makes a Good Commercial Security
Strata office units in the CBD and its fringe corridors are the clearest case: liquid market, institutional buyer universe, reliable valuation comparables. Conservation shophouses carry a heritage premium that has tended to support stable valuations, which can make them reliable bridge security.
Light industrial and logistics units in designated zones are also eligible, provided the tenancy covenant or occupancy position is solid. For a worked example of a prime Singapore commercial acquisition bridged ahead of a conventional refinance, see our Geylang case study.
The exit logic matters more than the asset type. A sitting tenant with an institutional buyer lined up is a materially stronger proposal than a vacant property with a vague disposal plan. Borrowers should state clearly: sale within the term, commercial bank refinance once the asset is stabilised, or lease-up to a rental yield that supports long-term hold.
When This Tool Fits and When It Does Not
A commercial bridge is right when the gap is one of eligibility or timing, not fundamental viability. The deal must make sense at the asset level: fair acquisition price, LTV within reach, and an exit that is realistic within a 3 to 24 month window.
It is the wrong instrument when the exit depends on conjecture: a market rerating that may not arrive in time, a refinance that assumes bank appetite the borrower cannot evidence, or a development return still on paper. Private bridge pricing reflects the short term and the asset-led underwriting behind it. That cost only makes sense for a borrower with a credible plan.
To understand how the lending process works from first call to drawdown, the timeline is straightforward: term sheet within 24 hours, drawdown in about two weeks. For more on how short-term private structures address TDSR-constrained borrowers, this overview of short-term property loan options covers the mechanics in depth.
Get Funding Approval Within 24 Hours
Speak with our specialists about your bridging requirements.
Frequently asked questions
Article sources1
Rikvin Capital cites primary, authoritative sources to support the information in our articles. The references below link directly to the original material.
- MAS. TDSR framework