 Photo by Jisun Han on Unsplash
Your facility is approaching its maturity date. The sale has not completed, the bank refinance has stalled, or the listing proceeds are still sitting in escrow. The original loan did its job. The exit has not.
Any new bank facility is re-tested under TDSR, and the calendar does not care that you already own the asset.
That is the part most explainers skip: what happens to bridge finance loans in Singapore when the planned exit slips, and whether a second facility, a tighter tenor, or a sale is the honest next step.
When the first facility matures and nothing has closed
The original use case was clean. You bought before you sold, you completed at auction, or you waited for a bank to finish its credit process. Then the buyer delayed and the committee asked for another pack of documents. A listing that looked firm in month four is still on the market in month eleven.
Private bridge finance loans are sized to a defined exit, not to a hope that something will turn up. When that exit slips, the first question is whether the security is still first-charge quality and whether a new exit can be evidenced. Rate nostalgia is not a credit argument.
How a takeout is actually underwritten
A second facility is a new loan, not a courtesy rollover of the first. We revalue the property and re-read the exit. If LTV still works and the new story is contractual, bridge finance loans can take out the first lender inside a 3–24 month tenor, interest serviced or rolled-up.
Banks apply the TDSR framework to declared income. We do not. That is why an accredited investor whose bonus, overseas earnings or retirement cashflow would fail a bank test can still be assessed on the asset. For the comparison, see bank versus private bridging loans in Singapore.
If the file needs to move, the lending process is valuation, KYC, source of funds and security, not a salary multiple. Terms remain indicative and subject to valuation and due diligence.
When a second facility is the wrong tool
If a fresh valuation cannot support the LTV, or the planned exit is a price the market has already refused, a re-bridge only postpones a sale you should be running now. Short-term money costs more than a term mortgage. Using it to wait for a number that has not arrived is how a timing problem becomes a capital problem.
Selling, cutting the ask, or injecting equity is sometimes the right answer. We will say so. Related: how we funded a Holland Road prime residential bridge.
What to have ready before the existing tenor expires
Bring the current facility letter, title, and any existing valuation. Add evidence of the delayed exit: an Option to Purchase, a sale and purchase agreement, a bank offer, or a listing report that is actually converting. KYC and source of funds for the borrower and any SPV sit on the critical path.
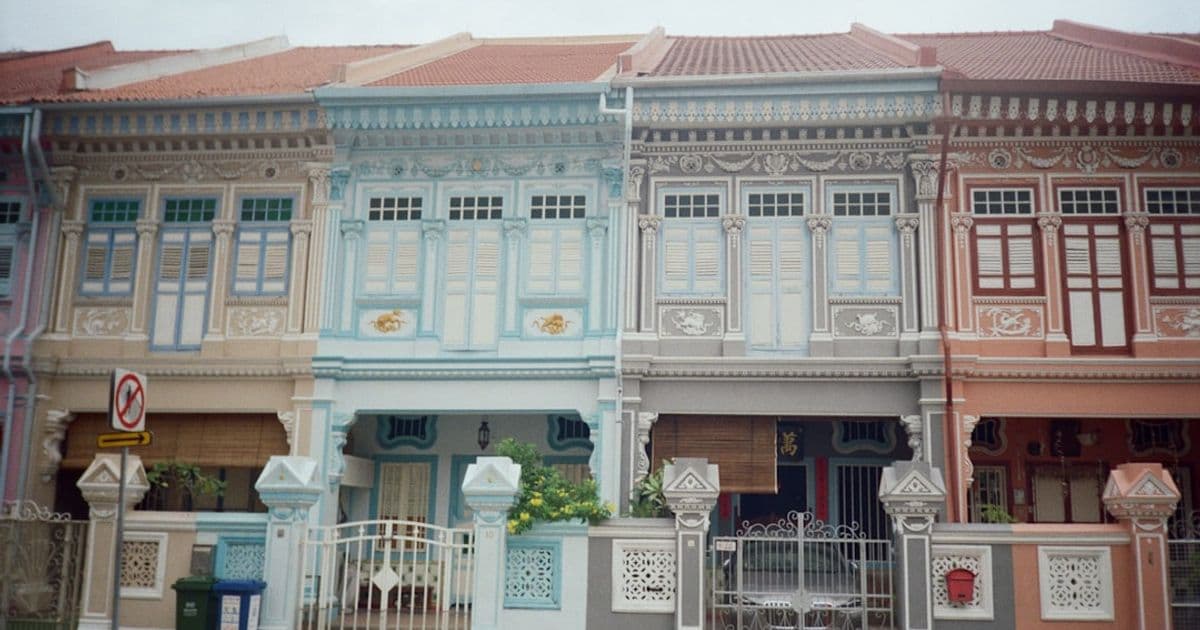
Landed security is underwritten on the asset, not on a payslip. If the charge is a Good Class Bungalow, start from GCB bridging loans. Conservation shophouses add URA conservation requirements to the due diligence; the same asset-and-exit test applies, just with extra documents.
The bottom line
A slipped exit is a credit problem with a clock on it. Treat it as one while you still have time to choose the tool, rather than having the maturity date choose it for you.
Get Funding Approval Within 24 Hours
Speak with our specialists about your bridging requirements.
Frequently asked questions
Article sources1
Rikvin Capital cites primary, authoritative sources to support the information in our articles. The references below link directly to the original material.
- MAS. the TDSR framework