Insights on Bridging Finance
Market commentary and explainers from the Rikvin Capital team across Singapore and the United Kingdom.
Global insights
Business Bridging Finance: Refinancing a Corporate Facility the Bank Won't Renew
Your bank will not renew the facility and the repayment date will not move. Business bridging finance refinances against property the company already owns, in Singapore and the UK, while you arrange the exit.
View details
Development Exit Finance: A Worked Example of Facility Cost vs a Price Cut
Construction debt is due and units remain unsold. This development exit finance case study puts the all-in cost of a 3–24 month facility against the price cut a forced sale would take, in Singapore dollars and in sterling.
View details
Auction Finance for Value-Add Lots: How Lenders Underwrite a Refurbishment Exit
You've found a discounted lot at auction; the exit is a refurbishment, not a sale at hammer price. Private lenders assess this differently: the security is today's value, the exit logic is the post-works GDV. Here is how the underwriting actually works.
View details
Commercial Bridging Finance: When Lease Risk Rules Out a Mortgage
Short leases, departing tenants, and imminent voids stop a bank from lending even when the underlying asset is sound. A private lender underwrites against collateral value and a clear exit instead.
View details
Business Bridging Finance for MBOs: Completing the Deal When Term Debt Isn't Ready
Your MBO has a signed SPA and a fixed completion date. The term debt is weeks from drawing. Business bridging finance against the target's commercial property can fund completion in 2–3 weeks while the long-term capital structure catches up.
View details
Bridging Loan vs Commercial Mortgage: When the Asset Decides, Not the Borrower
A vacant or mid-refurbishment commercial asset cannot qualify for a commercial mortgage, regardless of borrower strength. Understanding why the asset governs the choice saves time and deal costs.
View details
Bridging Loan vs Mortgage: Why Your Holding Period Decides the Cheaper Debt
You can qualify for a mortgage, so why pay bridging pricing? Because lock-ins and early repayment charges can wipe the cheaper coupon on a short hold in Singapore and the UK.
View details
Second Charge Residential Bridging: When the Maths Favour a Second Loan Over Breaking Your Mortgage
Breaking a fixed-rate mortgage triggers an early repayment charge that can exceed the total cost of a short-term bridge. Here is how to run the comparison, and when a second charge residential bridging loan is the cheaper instrument.
View details
Auction Finance for Non-Standard Lots: When the Property Itself Rules Out a Mortgage
Your auction lot clears in the room but fails at any bank on the asset itself, not the timeline. Private lenders underwrite non-standard lots on current value and exit clarity, making auction finance in London and Singapore viable where mainstream lending won't go.
View details
Development Exit Finance: How Lenders Underwrite a Finished Scheme When the Sales Clock Is Already Running
Your construction facility is expiring and the units are not yet sold. Here is how a private lender underwrites a finished scheme: what documents they need, how fast they move, and what separates a credible exit from a speculative one.
View details
Commercial Bridging Finance Calculator: What Inputs Actually Decide Your Loan Cost
Five inputs separate a commercial bridging finance calculator from a residential one: LTV basis, interest structure, fee stacking, retention and exit timing. Here is what each means for your deal cost.
View details
Commercial Bridging Finance Rates: How Asset Class, Void Risk and Exit Clarity Set Your Quote
Your commercial bridging quote came in higher than expected. Here is the lender's reasoning: asset class, void risk, WAULT and exit route complexity all move the rate before LTV is even discussed.
View details
Development Exit Finance Rates: What Moves the Price on a Completed Scheme
Your scheme is complete and units are selling, but construction debt is still expensive. Development exit rates are not a fixed tariff; they move on LTV, sales coverage, exit timeline, and charge position. A developer who understands those levers can negotiate a sharper price.
View details
Short-Term Asset Finance: The Cost of Waiting When a Deal Has a Deadline
Your deal has a deadline the bank cannot meet. In Singapore, an OTP gives weeks; in the UK, an auction gives 28 days. Here is when private short-term finance is the cheaper option.
View details
Property Loan True Cost: How Rate, Fees and Retention Combine Before a Single Penny Is Deployed
A private property loan has four pricing components, not one. Here is how monthly rate, arrangement fee, exit fee and interest retention interact, and why the effective cost on deployed capital regularly diverges from the headline figure.
View details
Commercial Bridging Finance: Funding a Property Before the Rent Roll Exists
Your commercial property is vacant or pre-let, and no income means no conventional mortgage, regardless of how strong the asset is. A bridge fills the gap, lending against current value while you secure the tenant that unlocks the exit.
View details
Pre-Approved Auction Finance: What a Private Lender Confirms Before the Hammer Falls
Most bidders arrange finance after winning the lot. Those who arrange it before hold a real edge: a verified ceiling, written confirmation the asset is lendable, and a lender already in motion before the completion clock starts.
View details
From Bridge to Mortgage: How Lenders Assess Your Refinance Exit Before They Fund
You plan to refinance into a mortgage once the bridge closes. Your bridging lender is already stress-testing that exit before they fund. Here is what gets assessed, and how Singapore and UK borrowers can de-risk the sequence at origination.
View details
Bridging Finance vs Business Loan: How Corporates Choose When the Deal Has a Hard Close
Your bank cannot meet the closing date. A bridge is underwritten against the asset and the exit, not your accounts, which is why it closes in weeks when a business loan takes months. Here is the framework for making that call.
View details
Land Acquisition Bridging: Funding a Plot Purchase When Mainstream Lenders Won't Move
Bare land produces no income, so mainstream lenders either decline or offer sub-50% LTV after months of processing. Here is how private lenders underwrite a land acquisition bridge, which exits work in Singapore and the UK, and when it is the wrong tool.
View details
What Is Development Exit Finance: Avoiding a Distressed Sale When Construction Debt Matures
Construction debt matures; units have not sold; a bank term mortgage is not yet available. Development exit finance refinances the facility at completion, buying the time to transact at full value rather than at distressed pricing.
View details
Bridging Finance vs Commercial Loans: Why the Asset's Income State Drives the Decision
If a bank has declined your commercial deal, the reason is almost certainly the property's income state, not your credit profile. This piece explains the bridging finance vs commercial loan decision and when each instrument is the right tool.
View details
Bridging Finance for Land: Why Planning Status Is Your Lender's First Question
Land has no income, no tenants, and no standard mortgage market as an exit. Planning status, consented or speculative, is the single factor that determines whether a private lender can fund your site at all.
View details
When a Bridge Loan Beats Using Your Own Cash: The Capital Efficiency Case
You have the liquidity. The deal is ready. And borrowing short-term might still be the sharper financial move. Here is when a bridge loan is a deliberate capital-efficiency choice, not a fallback, for investors running concurrent positions in Singapore or the UK.
View details
Rolled-up vs serviced interest: what each structure costs a bridging borrower
Rolled-up and serviced interest produce very different cashflow demands on the same bridging loan. This guide explains what each structure costs, when each fits the deal, and how lenders assess both.
View details
What replaces income in private lending: how an asset-backed deal gets underwritten
When income proof fails the bank's test, private lenders shift the underwriting question entirely: from salary serviceability to asset quality and exit credibility. Here is what that process actually looks at.
View details
What private credit can't solve: Singapore HNWIs and the case for bridging loans
Family offices with private credit relationships still reach for Singapore bridging loans when deal structure is the barrier. Short tenors, SPV ownership, and ticket-size mismatches create gaps that no credit fund can fill.
View details
How interest retention reduces your bridging loan proceeds
Interest retention deducts the full term's interest from gross loan proceeds at drawdown, so the net advance is materially less than the headline loan amount. Understanding this gap, and how to size the gross loan to meet a target net figure, is essential before signing any term sheet.
View details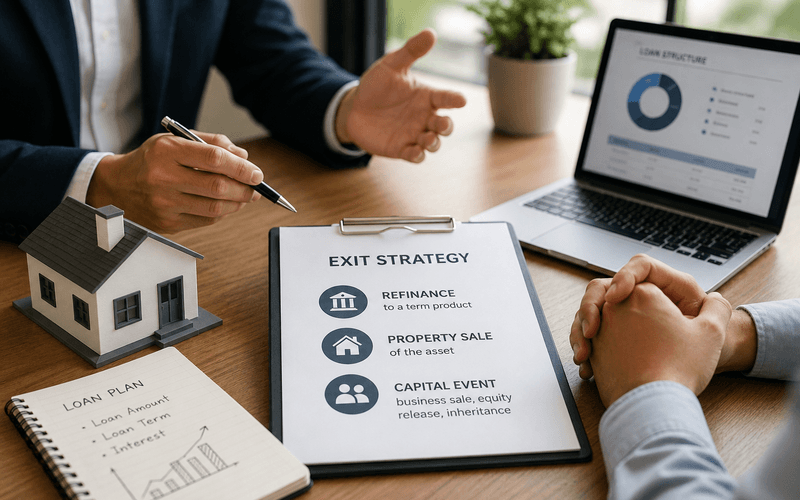
Bridging loan exit strategies: how lenders assess yours before saying yes
Private lenders underwrite against the asset and the exit, not the borrower's income. Your exit strategy determines whether a deal proceeds, at what LTV, and on what terms. This covers the three main exit types, what makes each credible, and what documentation to prepare.
View details
Rolled-up vs serviced interest: what each structure costs a bridging borrower
Rolled-up and serviced interest produce the same total cost over an identical term but differ sharply on cash outflow, available loan size, and the balance due at exit. A plain-numbers comparison for bridging borrowers in Singapore and the UK.
View details
Bridging Finance: When to Use It Instead of a Bank Loan
A bridging loan fills the gap between needing capital now and a longer-term solution arriving later. Here is how it works, when it beats a bank loan, and when to think twice.
View details
How long a bridging loan really takes, from enquiry to drawdown
Your bridging loan can draw down in two to three weeks, or inside seven days if preparation is right. This is what every stage of the process actually takes, and where delays really come from.
View details
What a bridging loan actually costs, and what drives the price
Bridging loans are quoted monthly, and the headline rate is only one of four cost components. This guide explains what drives the price, what else to budget for, and when the total is worth bearing.
View detailsSingapore insights
View all Singapore insights →
Bridging Loan Against Shares in Singapore: When It Beats a Margin Facility
Your SGX position is concentrated and your margin facility is at its ceiling. A Singapore bridging loan against the same shares is fixed-term, not callable on volatility, and assessed on the equity value and your exit plan rather than income.
View details
Bridge Lenders for Singapore Commercial Real Estate: When TDSR Leaves No Room for the Deal
Your residential mortgages have maxed your TDSR and the bank will not touch the strata office or shophouse you want. A bridge lender for commercial real estate assesses the asset and exit, not your debt-service headroom.
View details
Family Property Buy-Outs in Singapore: Bridge Lending When Co-Owners Can't Agree to Wait
When co-owners can't agree to wait, one sibling can buy the rest out before an open-market sale is forced. A Singapore bridge funds the buy-out in weeks; bank refinance follows once sole title transfers.
View detailsUnited Kingdom insights
View all United Kingdom insights →
UK Bridging Loan Interest Rates: What Foreign Buyers Pay Beyond the Headline Quote
Decode your UK bridging term sheet: what a monthly rate compounds to, how arrangement and exit fees change the total, and how to compare a UK bridge against your home-market annual quote.
View details
UK Developer Exit Finance After a GDV Shortfall: When Your Lender Won't Extend
Your scheme has reached practical completion but your construction lender has flagged a GDV shortfall and will not extend the facility. Developer exit finance from a private lender replaces the debt at current value while the sales campaign clears it.
View details
UK Non-Dom Reform and Bridging Finance: The Property Restructure Gap
The April 2025 abolition of the remittance basis is forcing long-term non-doms to restructure UK property holdings. Each structural move creates a financing gap no high-street lender will touch. A bridging loan for a foreign national covers the transition, assessed on asset and exit.
View detailsDiscuss an Asset-Backed Funding Scenario
Share the article, asset and timeline you have in mind. We will review whether a private facility may be suitable.