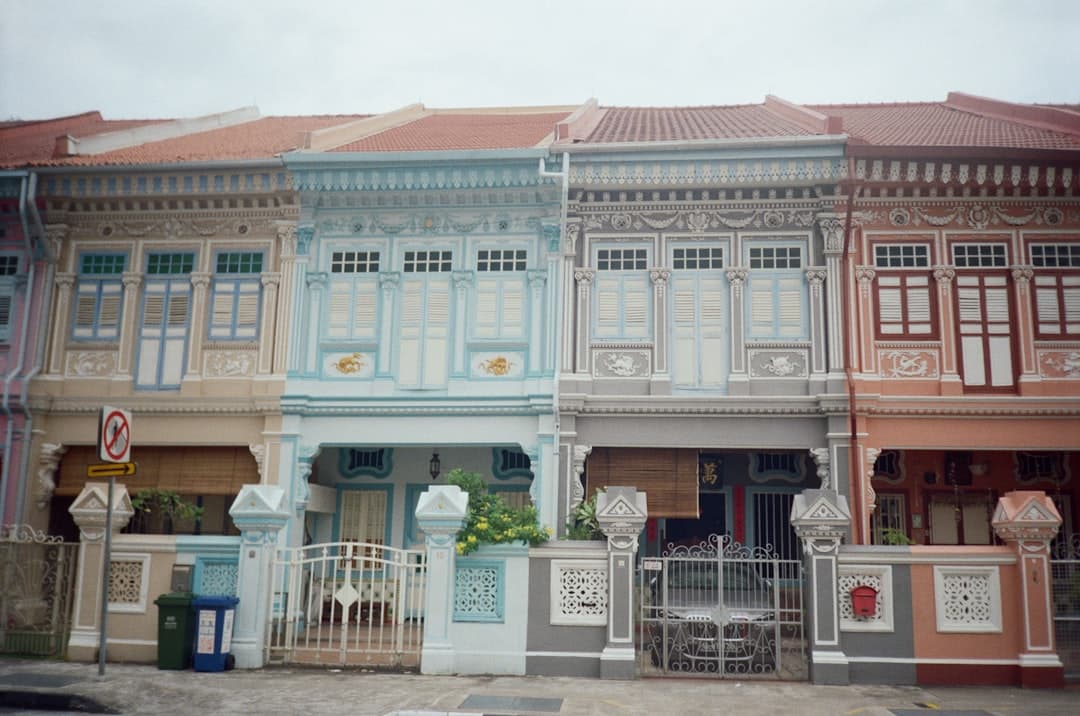
 Photo by Jie Yeu Teoh on Unsplash
You've identified a lot at auction priced below its potential. It needs work: a refurbishment, a conversion, a conservation upgrade on a heritage shophouse. The opportunity is the gap between today's hammer price and tomorrow's GDV. The financing question that follows is different from a clean auction purchase, and most guides don't address it.
Standard auction finance gets a borrower to completion within the 28-day window. It assumes the exit is a sale at or near current value, or a refinance once the property settles. But if your exit depends on works completing first, the lender's security today and your exit value in 12 months are materially different numbers.
Private lenders experienced in Singapore mortgagee sales, UK auction rooms, and negotiated distress deals treat this as a two-stage credit problem. Understanding how they think about it saves you from a structure that looks affordable until the works bill arrives.
What the Lender Sees When the Exit Is Not Today's Property
When you bid on a discounted or distressed lot, the asset you're acquiring has a clear present-day value. Take a Singapore shophouse needing conservation-grade restoration, an older condo block sold through a mortgagee process, or a UK commercial unit with an EPC that currently rules it out for residential letting. Each is worth less today than it will be after the works. The lender charges against today.
The LTV calculation at completion is straightforward: secured against the as-is valuation at the hammer price. That part of auction finance in Singapore or UK auction bridging is identical to a clean acquisition. The divergence appears the moment you explain that your exit depends on a transformation the lender cannot yet value.
A private lender assessing this deal asks two questions at the outset. First: is the as-is LTV defensible without any credit given to the works? Second: is the exit a credible event at a credible timeline? If either answer is unclear, the facility does not price the same way, and it may not be available from the same lender.
How the Underwriting Differs from a Clean Auction Purchase
For a standard auction lot, the credit inputs are LTV, clear title, and a plausible exit at or near current value. For a value-add deal, three additional inputs define the underwriting.
Works quantum. Light cosmetic refurbishment (decoration, kitchen, bathrooms) is a different risk profile from structural conversion or a conservation-prescribed restoration under URA's conservation guidelines. Lenders distinguish between these because the second category carries regulatory dependencies that can delay or change scope mid-works. A contractor quote and programme will be required before a lender accepts your GDV assumption as a credible exit.
Exit route. Sale and refinance are not interchangeable on a value-add lot. A sale exit requires a credible buyer pool for the finished product and a verified comparable GDV. A refinance exit requires the completed asset to qualify for a long-term facility. In the UK, that means mortgageable condition and clear title registered with HM Land Registry, with EPC compliance relevant where the exit involves a letting use. In Singapore, a refinance exit at a higher GDV depends on the refinancing bank satisfying its own TDSR assessment against the improved value. That is not Rikvin's constraint as a private lender, but it is the exit buyer's lender's constraint.
Planning position. For commercial-to-residential change of use in the UK, permitted development rights (where they still apply) compress planning risk significantly. Without them, a lender wants consent in hand, not pending. A pending application converts a credible 12-month exit into an uncertain 18-to-24-month one.
When all three are clear, the structure is straightforward: a completion bridge against as-is value, with the GDV acknowledged as the exit logic rather than the security basis. When any of the three is ambiguous, the deal either prices higher or waits. If you're assessing a lot before the auction date, speak with our team so the credit conversation runs in parallel with your due diligence.
When This Structure Works, and When It Does Not
The structure works when three conditions align. The hammer price must represent a genuine discount to neighbourhood GDV; the works scope must be defined and costed; and the exit must not depend on external events going the borrower's way.
It breaks when buyers conflate "bought below market" with "low credit risk." An auction lot may have cleared at a discount because the works are more expensive than the lot description suggests, or because the title carries restrictions that complicate resale. The finished product may also have a thin buyer pool in that location. None of this is visible from the hammer price.
The margin on a value-add auction facility sits above a clean acquisition. But the real cost calculation starts with the works budget and the realistic GDV, not the interest rate alone.
The scenario where auction finance is not the right instrument: if planning consent is pending, or the refurbishment timeline realistically exceeds 18–24 months, you are financing a small development, not a bridge. Attempting to roll a short-term bridge into a development facility mid-works adds cost and timeline pressure at the worst possible moment. A development finance structure, agreed before the works start, is the cleaner answer for that risk profile.
Where the value-add case is clear, the exit plan and the security get assessed together from the first credit discussion rather than sequentially. The £18.8 million West London hotel facility shows how that works in practice on a complex asset.
The adjacent piece on auction finance for non-standard and unmortgageable lots addresses a related but distinct problem: when the asset itself, not the exit strategy, is the source of lender caution.
Get Funding Approval Within 24 Hours
Speak with our specialists about your bridging requirements.
Frequently asked questions
Article sources2
Rikvin Capital cites primary, authoritative sources to support the information in our articles. The references below link directly to the original material.
- URA. URA's conservation guidelines
- GOV.UK. HM Land Registry